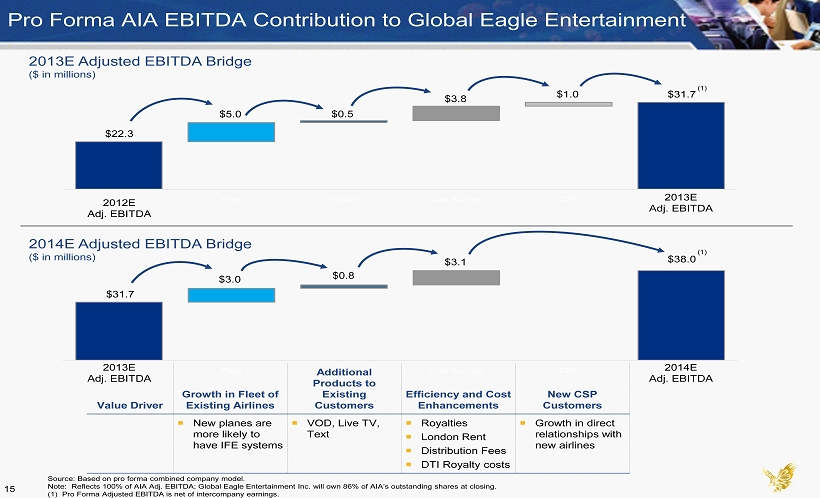
As readers of this blog know, I’ve not been a fan of Row44′s content-focused strategy for inflight connectivity, and I pointed out how ludicrous Global Eagle’s forecasts were last November. However, the meltdown of this strategy has come even sooner than I expected, with today’s announcement that instead of charging for streaming video content on Southwest planes, the service will instead be sponsored by DISH Network and made available for free to passengers, in exchange for watching a 30 second commercial.
The fact that Row44 has struck this deal now, only a few months after launching the inflight TV service, suggests that the paid take-up has been dire (which is hardly a surprise, given the Southwest customer profile, their average flight length and the lack of onboard power outlets). Even worse, according to DISH’s CMO, the sponsorship has no announced end date (although it will run at least through the end of this year), suggesting that instead of being a temporary deal to boost awareness (like Gogo’s Thanksgiving to New Year 2010 free inflight WiFi offer, sponsored by Google), it may never be possible to get many passengers to pay for the service. This move may also be a pre-emptive counter to JetBlue’s plan to offer free inflight WiFi to its passengers, but will do nothing to boost take rates for Row44′s paid internet service, and will more likely undermine them now that Southwest passengers can instead watch video content for free.
The business projections presented by Global Eagle last November (setting out their supposed “highly visible” 2014 adjusted EBITDA forecast) estimated that the TV/VOD/IPTV service would have a take rate of 5.75% and generate $5 per user in 2014 (i.e. $0.29 per passenger opportunity), plus a further $0.15 per passenger in portal services. Although DISH has not revealed its sponsorship payment, according to my calculations based on Gogo’s S-1 filing, Google paid $7M for its 6 week sponsorship, or roughly $0.28 per passenger carried (about $2.50 per Internet session) during the period. Its a safe bet that DISH is paying a lot less than that for an ongoing deal: I’d estimate roughly $1M per month (~$0.10 per passenger carried), or about a third of Global Eagle’s projection for revenues from these services in 2014.
UPDATE (7/1): It was pointed out to me that the sponsorship deal is between DISH and Southwest, so it’s not clear how much of DISH’s sponsorship payments are being passed on to Row44 or indeed if Southwest will be making additional payments to Row44 to subsidize the TV service. That is possible, but its hard to believe that Southwest would want to provide a large subsidy to Row44 for an indefinite duration, when Southwest originally expected to be receiving a share of revenues, just like from inflight WiFi (and when Gogo is offering airlines a ~30% revenue share from its Gogo Vision services).
UPDATE (7/3): Global Eagle confirmed in a press release that “its Row 44 subsidiary has entered into a groundbreaking content and connectivity partnership with its customer Southwest Airlines” or (without the spin), that Row44 has changes the terms of its TV services agreement with Southwest, presumably to a flat fee rather than a revenue share. Undoubtedly this means a reduction compared to Row44′s projected 2014 revenues, although when the next set of financial results come out, look for further spin describing the change as providing a significant boost to revenues in 2013Q3 (compared of course to the near total absence of content revenues in Q2).
Based on Gogo’s published data, revenue from portal services is also going to be vastly less than Global Eagle estimates, while there has also been “an increase in license fees paid for the content delivered to airline customers” (which are unlikely to reduce, even if revenues are lower than expectations) and bizarrely, Global Eagle appears to have ignored any revenue share that may be payable to Southwest in its assumption of a 87% gross margin on content services. By my estimates, even ignoring any negative impact on Row44′s connectivity revenues from the free TV offering, that could leave a $30M to $40M hole in Global Eagle’s projected $75M of adjusted EBITDA in 2014. Put another way, it seems that this business really wasn’t “highly visible” after all.
Now that Clearwire’s board has urged its shareholders to reject the Sprint bid, and Sprint has initiated litigation to try and block DISH’s tender offer, it seems Charlie Ergen has a good chance of achieving his objective: to ensure Sprint is unable to make use of Clearwire’s spectrum and enhance its network capacity as SoftBank desires. DISH has indicated that it will now focus on its Clearwire tender instead of making a further bid for Sprint in advance of today’s deadline.
While that doesn’t rule out DISH making another higher but unfinanced offer to disrupt the Sprint-SoftBank vote next week, it seems Ergen might be better off having SoftBank complete a takeover of Sprint and then discover that its $21.6B investment will go to waste unless Sprint agrees to sell DISH the 40MHz of Clearwire’s spectrum that Ergen wants.
So I’m left wondering if DISH’s actions have all been part of a grand plan:
a) keep making offers that persuaded Clearwire shareholders (and ultimately the Clearwire board) to reject the Sprint takeover
b) make an uncommitted bid for Sprint to persuade SoftBank to overpay for Sprint
c) make noises about LightSquared’s spectrum to persuade Sprint to raise its bid for Clearwire by less than expected
d) come in with a much better offer for Clearwire shares at the last minute, which was high enough to ensure that the Sprint bid for Clearwire will be rejected
e) hedge the bid with just enough conditions that will ensure that Sprint is unable to make use of Clearwire’s spectrum and that Clearwire, DISH and Sprint are tied up in litigation for months to come.
Given that sequence of events, its reasonable to ask if SoftBank really wants to own Sprint without the Clearwire spectrum? If not, then will SoftBank have any option other than to ultimately do a deal with Ergen on his terms? If you think that’s unlikely, then you only need look back to the Cablevision-DISH trial over Voom last fall, where DISH had a terrible position in the courtroom, but still managed to get to a settlement which achieved Ergen’s objectives (including a purchase of the MVDDS spectrum which will be part of DISH’s planned wireless broadband network).
After all, remember that DISH still has a number of options to make SoftBank’s life even more miserable, including mounting a rival bid for the PCS H-block spectrum which Sprint desperately needs to enhance the capacity of its existing LTE network.
So maybe the question is now when not if SoftBank will be forced to settle with DISH? As Vijay Jayant told The Hollywood Reporter in April “Charlie’s attitude is, ‘At some point, they’ll negotiate with me on my terms.’ He’s bluffing until he’s not.”
Please Masa, don’t throw me into the litigation briar patch!
This week saw an apparent reversal for DISH on Monday, when SoftBank agreed to increase its bid for Sprint slightly and Sprint rejected DISH’s bid as unlikely to lead to a “superior offer”, followed by a victory on Wednesday when Clearwire’s special committee recommended that shareholders accept DISH’s $4.40 per share tender over Sprint’s $3.40 per share bid to buy out minorities.
Despite this apparently split decision, many seem to believe that the outcome will have to be all-or-nothing, with either DISH or Softbank winning both Sprint and Clearwire. In other words, either Sprint increases its bid for Clearwire to fend off DISH, or DISH brings in an equity partner to further improve its bid for Sprint. However, Sprint has put some serious roadblocks in DISH’s way, increasing the break-up fee due to SoftBank if its bid is rejected and more importantly, requiring any counterbid by DISH to be “fully financed pursuant to binding commitments from recognized financial institutions“. Sprint has also stated that it will “enforce its governance rights in Clearwire” and previously described DISH’s offer for Clearwire as “illegal”.
In my view, rather than pointing towards a new DISH bid for Sprint with committed financing (costing hundreds of millions of dollars) which would potentially still be rejected by the Sprint board, that suggests to me that DISH might instead make a much higher (non-financed) bid for Sprint and then initiate legal action over Sprint’s refusal to consider it. Similarly, DISH has been trying to delay FCC approval for the SoftBank bid, because Softbank has been emphasizing the urgency of moving forward quickly to improve Sprint’s network and the deal becomes less attractive to SoftBank the longer it is delayed. Going forward DISH would presumably also bid against Sprint for the H-block spectrum, closing off yet another avenue for Sprint to improve its network.
A similar strategy may be at work in the Clearwire bidding, and even if Sprint was to mount an increased bid (which seems less likely now that SoftBank has increased the offer to Sprint shareholders and reduced the cash available to Sprint for investment), I’m convinced that Ergen would simply increase DISH’s tender offer once again. As a result, DISH is very likely to gain a substantial stake in Clearwire, and then Ergen will be able to block Sprint from taking full advantage of Clearwire’s spectrum, and probably tie the company up in another legal battle over Sprint’s “governance rights”.
Remember that as Craig Moffett noted “Dish is unique in that it uses litigation as a profit center” and Charlie Ergen said last year “I may be the only CEO who likes to go to depositions…You can live in a bubble, and you’re probably not going to get a disease. But you can play in the mud and the dirt, and you’re probably not going to get a disease either, because you get immune to it. You pick your poison, and I think we choose to go play in the mud.”
So now the question for Masayoshi Son is, does he want to tie up Sprint and Clearwire in litigation for years, or will he instead reach an accommodation with Ergen, and sell DISH the 40MHz of Clearwire spectrum that Ergen wants, in exchange for getting full control of Sprint and the remainder of Clearwire? Such a deal might enable Ergen to become a wireless competitor (as it would likely be followed by DISH purchasing T-Mobile), but the alternative may be that SoftBank’s $21.6B investment in Sprint wastes away, as Sprint fails to improve its network and does not become any more competitive with AT&T and Verizon.
So the question is who holds the LightSquared LP Preferred Shares, which I was told were sold to Ergen/Sound Point by Fortress and Providence in April when they sold their Term Loan debt. Notably, Solus (who have been on the opposite side from Ergen in previous MSS bankruptcies) has also sold its LP Preferred holdings in recent months. So its pretty clear that there is likely a single large undeclared holder controlling virtually all of the fulcrum security in this bankruptcy. Is it DISH (perhaps holding the preferred shares directly rather than through Sound Point) or someone else? And what happened to the indications I’d received that Sound Point owns more than half of the Term Loan? Is there another undisclosed Sound Point fund (perhaps backed by Carlos Slim?) in addition to SPSO that controls an additional $300M to $400M of the term loan? Its going to be very interesting to see how this works itself out and who now owns what, as we look forward to another epic legal battle over LightSquared’s proposed reorganization plan.
Gogo’s IPO roadshow is taking place this week (with completion apparently expected next Tuesday) after the company filed a revised S-1 on Monday June 10 indicating that it is seeking to sell 11M shares at between $15 and $17, giving the company an enterprise value (at the midpoint of this range) of approximately $1.3B (or even higher if you assume, as Gogo does, that the cash it raises needs to be spent on upgrading Gogo’s network to ATG-4, including doubling the number of cell sites by 2015). That seems pretty optimistic given the modest revenues that Gogo generates at present ($235M in 2012) and the losses that the company is making outside its well established Business Aviation segment.
I’ve not yet completed my forthcoming aeronautical communications market report, but I know a lot of people will be looking for some realistic numbers to value the company. So I decided to pull together my detailed estimates for Gogo through 2017, into a 21 page profile and analysis which I’ve published today. You can find a report summary and contents list here, and an order form here. And if you decide to buy my aeronautical market report when its available later this summer, you’ll receive a full credit for the price of the Gogo report.
Feel free to contact me for more details. As a taster, here’s the latest quarterly growth breakdown including 2013Q1. The last quarter is quite significantly short of my estimates, as despite the improving take rate trend line, Gogo took a significant hit on Average Revenue Per Session compared to 2012Q4.
UPDATE 6/13: And here is a comparison with the various analyst forecasts for Gogo which were given out at the roadshow. I’ve left off the names, to spare people’s blushes, but the bank that forecast this to be a $1.6B business in 2017 has clearly been drinking the same Kool Aid as Global Eagle.
Some observers may be wondering if Charlie Ergen is serious when he suggests using LightSquared spectrum as an alternative to Clearwire, as suggested by today’s news that DISH made a $2B cash bid last week to buy LightSquared (note that the offer is for LightSquared LP not Inc, i.e. ignoring the 1670-75MHz Crown Castle lease). After all, some might think this is yet another in a series of increasingly implausible maneuvers, as DISH tries desperately to find a way to exploit its spectrum assets.
However, its important to note that this story comes immediately before Clearwire shareholders were set to vote on Sprint’s bid for the company. That’s curiously similar to the leak of news that DISH was interested in buying T-Mobile (also to Bloomberg), just a few days before DISH made its bid for Sprint last month, so I wonder what Charlie Ergen has in mind this time around.
In the case of LightSquared, the company still has exclusivity to propose a plan until the end of this month, while DISH has indicated that its offer only remains valid until May 31, so DISH has plenty of outs if it wants. In addition, its hardly likely that Harbinger would accept an offer that would wipe out their equity, even if value is left for preferred holders (where Sound Point owns an 80% stake and would thus control the fulcrum security in any reorganization) after paying off the $1.7B plus interest due on the term loan.
LightSquared’s spectrum is certainly not a near term alternative to Clearwire, given that it will take years for use to be approved, and an L-band ecosystem won’t develop until well after that for DISH’s AWS-4 spectrum. On the other hand, the L-band has near term value to DISH because of the Mexican situation, and could be a long term backup option, if DISH plans to sit on its AWS-4 holdings for the next several years and wants to reband it to downlink spectrum, so its worth forcing Harbinger’s hand and ensuring that LightSquared’s assets are ultimately auctioned off.
However, just as the T-Mobile story was a red herring to distract from DISH’s planned bid for Sprint (even though it remains a possible alternative option for DISH), I wonder if the LightSquared story indicates that DISH has another plan to announce in the next few days. Could it be a deal to buy spectrum from Clearwire, if Sprint’s bid is unsuccessful? Certainly the suggestion that LightSquared is a viable option might help DISH in negotiations with Clearwire over price.
Another possibility is that DISH is trying to persuade Clearwire shareholders to sell out to Sprint for a relatively lower price, on the basis that DISH could then go all out to buy Sprint, without worrying about Crest trying to hold out for more money for Clearwire investors. Finally, and perhaps the biggest stretch: could DISH be poised to reach an understanding with SoftBank that it will gain control of some of Clearwire’s spectrum if SoftBank succeeds in buying Sprint and Clearwire without a significant increase in the current bids?
News tonight that Clearwire may decide to delay the vote on Sprint’s bid certainly suggests that Sprint might now succeed in securing the votes to buy Clearwire with only a modest increase in its bid price (to say $3.30 to $3.50 per share). In that case, DISH would have to either negotiate with or outbid SoftBank if it is to secure access to the Clearwire spectrum it wants, unless DISH succeeds in persuading the FCC that Sprint should be forced to dispose of some of Clearwire’s spectrum as a condition of closing the deal.
At least from SoftBank’s point of view, DISH would certainly be a more palatable purchaser of Clearwire’s spectrum than Verizon. If that presents too much of a problem (from the point of view of Sprint shareholders who would then be unable to realize the benefit of a rival DISH bid), could Sprint sell some 2.5GHz spectrum to T-Mobile instead, presenting DISH with another indirect route to acquire this spectrum?
Many epitaphs are being written today, and perhaps even a few pitches for book deals, bringing back memories of my comments to Bethany McLean for her Vanity Fair article two years ago. However, some apparently think the LightSquared saga has a few more chapters to be written, after Chairman Genachowski’s comments yesterday that “he expects LightSquared Inc. to eventually win approval for using its airwaves”. Since I actually asked him the question that prompted this statement (at the Jefferies conference) about what lessons he took from the LightSquared debacle (a characterization he disputed), I thought it would be useful to set the comment in context.
It was prefaced by the statement that Genachowski believed all satellite and broadcast spectrum was underused and should be reallocated for flexible terrestrial mobile broadband use, to meet the “obvious” spectrum crisis, and because of this “crisis” the L-band spectrum was “too valuable to be left unused”. Of course, he didn’t state any timeframe for action, and acknowledged that it was not possible to use the L-band spectrum without new receiver standards or similar changes to protect GPS (which will take years).
Recent actions, such as tomorrow’s NPRM on Qualcomm’s plan to use Ku-band satellite spectrum for Air-To-Ground communications and the effort to allocate C-band spectrum for small cells certainly bear out Genachowski’s lack of regard for satellite services, and so its not surprising that Globalstar has been urging him in recent days to move forward with an NPRM on its TLPS plan “prior to the Chairman’s expected departure later this month”.
In contrast, observers I’ve spoken with expect his successor, Tom Wheeler, to have a keen appreciation of the challenges associated with reallocation of spectrum, by virtue of his chairmanship of the FCC’s Technological Advisory Committee (whose February 2013 white paper on harm claim thresholds notably didn’t even mention attempting to solve the LightSquared/GPS conflict). I’m also told that given the battle that will take place with the DoD over gaining access to the 1755-80MHz spectrum for an auction next year, it is highly unlikely to be worth extending this fight to cover LightSquared/GPS as well.
So why was Sound Point, which is widely believed to be backed by Charlie Ergen, buying up LightSquared’s debt and preferred shares last month? After 3 days of meetings with dozens of investors in New York this week, I’ve been refining my view of Ergen’s plan for Sprint, Clearwire, LightSquared etc and will shortly be issuing the next update to last week’s report on DISH’s wireless ambitions. On the LightSquared front, what has emerged is that Sound Point has now acquired the majority of LightSquared’s Term Loan debt, and there appears to be reasonably wide consensus that both Ergen and Carlos Slim are backing Sound Point. I’ve also concluded that the near term focus is likely to be on the leverage that gaining control of LightSquared would give Slim to get a Mexican broadcast license, as part of a settlement with the Mexican government to resolve the dispute over spectrum allocation for MEXSAT. That could provide a windfall for Slim (and DISH Mexico) that is worth far more than the $600M-$700M that Sound Point has paid for what is likely to be a controlling stake in a reorganized LightSquared.
In those circumstances, there would be little point in Sound Point offering to buy out the rest of the term loan holders, and instead a debt for equity conversion of the LP Term Loan seems much more plausible. That would leave the remaining Term Loan holders with illiquid equity in an entity with only a very long term possibility of owning valuable spectrum (assuming that any further payments to Inmarsat can be deferred indefinitely until terrestrial usage rights can be established in the L-band) and perhaps some optionality based on future litigation. That might come as a big shock to those who believe that the only outcome is that the Term Loan will get taken out at par plus accrued interest, because of how important LightSquared’s spectrum assets are to Ergen!
Softbank has been downplaying the prospects of an increase in its bid for Clearwire, and my guess is that it will be prepared to let Sprint’s current bid be rejected in the May 21 vote, because its hard to see Clearwire’s shareholders approving a deal with Sprint with only a modest bump in the price (say to match DISH’s $3.30 offer). Then the question is whether Sprint (and SoftBank) would allow Clearwire to sell DISH the 40MHz of 2.5GHz spectrum that DISH has been seeking (with the likelihood that Ergen might then withdraw his bid for Sprint)?
Tonight an analyst report from Macquarie is speculating that DISH will instead team up with American Movil and bid for LightSquared, as an alternative to Clearwire (whose spectrum could then be sold to Verizon). While a partnership between Ergen and Slim is plausible (and indeed is something I’ve been writing about for the last year), using LightSquared’s spectrum as an alternative to Clearwire makes little sense (even if Verizon was able to buy all of Clearwire’s spectrum, which of course it can’t because the BRS spectrum is counted in the spectrum screen). Strangely, Macquarie thinks DISH could get 20MHz of uplink and 10MHz of downlink spectrum from LightSquared, but the 1675-80MHz spectrum won’t be allocated until 2017, and even if it were available, only 10MHz of downlink spectrum would be insufficient for DISH’s plans.
Our report on DISH sorts through the options for DISH, and discusses the reality of what can be done with LightSquared’s spectrum. We also consider the relative advantages of DISH and SoftBank’s plans for Clearwire’s spectrum. In particular, we consider one question that appears to have escaped all of the analysts looking at this situation: what is the value of DISH’s 14M potential cellsites?
If you’ve been wondering what I’ve been up to for the last couple of weeks (like Phil), I’m pleased to announce that I’ve been hard at work on a new report, released today, on DISH’s bid for Sprint, which discusses DISH’s plans, alternatives and the most likely outcomes from the battle with SoftBank. You can also read some of my thoughts in a GigaOm article (though its not very accurately titled – that wasn’t my choice) or listen to my interview on CNBC last week.
If you are interested in getting a copy of the report, and discussing my conclusions, then an order form and report summary can be found here or please email me for more details. If you’d like to meet in person, then do get in touch: I’ll be in New York next week from May 7-9, on a panel session discussing “Wifi – Friend or Foe of the Mobile Network?” at the Jefferies TMT conference (May 8th) and then at CTIA in Las Vegas from May 21-22, speaking at a Tower and Small Cell Summit panel on “Spectrum Acquisitions and Their Impact on Cell Towers” (May 21st).
UPDATE: A few early comments on the report:
“It was excellent; a really deep analysis. I cannot fault your conclusions and I actually learnt a lot from reading it.” Wireless company CEO
“Read your report this morning. It’s very good…I think your ideas are dead on” National tech reporter
The FCC’s proposed FY2014 budget, released on Wednesday, now appears to have sounded the death knell for LightSquared’s September 2012 spectrum swap proposal, that it should be granted access to the 1675-80MHz band, in exchange for giving up “rights” to deploy a terrestrial network in the 1545-55MHz downlink part of the L-band. Instead, the budget proposes that NOAA’s radiosondes should be relocated (presumably to the 400-406MHz band which is also used by weather balloons) and that the 1675-80MHz should then be repurposed using “either auction or fee authority” in 2017 to raise $230M.
This news seems to confirm what happened at the February 20 meeting between the FCC and LightSquared’s lawyers, is that the FCC told Latham & Watkins that they were going to propose reallocation of the 1675-80MHz spectrum for commercial use, but would deny the requested spectrum “swap”, so LightSquared would have to bid in an auction just like anyone else. Although the FCC has not yet issued a ruling (perhaps to avoid tarnishing Chairman Genachowski’s recent speeches about his legacy), release of an order may now be quite close, given the public disclosure of the FCC’s intentions in this week’s budget document.
In a statement to Communications Daily (who first reported this issue), LightSquared continued its usual practice of pretending that all is well, asserting that “What happened today is certainly consistent with our filings” because there would be costs associated with any “sharing agreement”. However, even if LightSquared did pay $230M for the spectrum (and I find it hard to conceive that the FCC would simply award the spectrum to LightSquared if other operators want to bid on it at auction), the 2017 allocation date is obviously far too late for LightSquared to proceed with its fantasy of an LTE network buildout.
UPDATE 3 (4/13): LightSquared’s ex parte for an April 3 meeting with Commissioner Pai indicates a different (and more telling) story, going back to LightSquared’s generic appeals from 12 months ago about the “compelling need to find spectrum-based, technical, legal, or other solutions to the current issues” and abandoning the 1675-80MHz proposed “swap”. Notably, this ex parte was not even filed in IB Docket 12-340, relating to LightSquared’s September 2012 request to modify its ATC Authorization, which would have been required if the 1675-80MHz “swap” was part of this discusssion. Instead LightSquared is now apparently going back to its demand for “regulatory approvals” to move forward with its original L-band plan and threatening legal action if that is not forthcoming.
Given the Mexican coordination issues, the implausibility of LightSquared gaining any more spectrum for free, and the potential costs for continuing LightSquared’s Cooperation Agreement with Inmarsat after March 2014, its fascinating to see how much excitement has built in the distressed debt community in the wake of the WSJ’s report last week that Sound Point had been buying up LightSquared’s debt and preferred stock. That is despite the fact that several large holders in the Ad Hoc Secured Group (not just Fortress) have now exited their positions.
I’m told that a target valuation of 130 cents on the dollar for LightSquared’s LP Term Loan debt is now being floated by some people, based on an assumption that Ergen would convert the secured debt to equity. Even if one believes that Ergen will get involved (as opposed to using LightSquared as a bluff to secure a deal with T-Mobile, MetroPCS, CLWR or Sprint), then that seems excessive, given that buying out the TL debt at par plus accrued interest would only give a valuation of 115 cents on the dollar at present, and any bankruptcy auction will presumably look a lot like TerreStar, where DISH bid just enough to buy out the secured debt (including Echostar’s holdings) at par, just as DISH would presumably buy out Sound Point and other holders for cash at par in a LightSquared auction.
After all, DISH has $10B in cash, and potentially not much to spend it on right now. Any DISH deal with T-Mobile would most likely have come before the recent price adjustment to TMO’s MetroPCS bid (not least because it would have made it more difficult for Paulson and PSAM to hold out for alternative suitors), and a counterbid for MetroPCS is harder now that MetroPCS’s stock price has risen. Similarly, a potential deal with Clearwire seems to be slipping away, as it takes more money from Sprint, despite the efforts of Crest to block Sprint’s bid.
What would be the form of a DISH deal with TMO? The four possibilities are:
a) a joint venture (like Clearwire) which wholesales capacity to DISH, TMO and potentially other players
b) a hosting agreement (like Sprint and LightSquared) with TMO taking payment in the form of capacity
c) an investment by DISH in T-Mobile (like Softbank and Sprint) through the contribution of cash and spectrum in exchange for a majority equity stake
d) a full merger of DISH and T-Mobile.
Of these, I think the first can be ruled out, for the same reasons that Clearwire has had so many problems: TMO would take most of the capacity, so would have too much influence, and it would have an incentive to only use the JV capacity after exhausting its own resources. The second can also potentially be ruled out, simply because the deal would have to be more advantageous to DISH than the LightSquared-Sprint agreement: TMO would cover most of the costs and take payment in capacity, not cash, and then DISH wouldn’t need $10B in cash. The fourth option is probably also less appealing (as DISH has hinted previously), because DT might insist that Ergen gives up the dual class share structure which gives him tight control over DISH, and the synergies between DISH’s satellite TV business and T-Mobile’s wireless business are far less compelling than a merger between DISH and AT&T (with its fixed line and U-verse business) would have been. If DISH stays as a separate company then a merger with DirecTV also remains a possibility, perhaps with DISH’s T-Mobile stake being spun off to Ergen if DirecTV buys out DISH.
So the third option sounds like the most plausible, and the question is whether Ergen can purchase a majority stake in a merged T-Mobile/MetroPCS in exchange for $10B in cash and potentially $8B to $10B in contributed spectrum value. This becomes a harder task after the MetroPCS merger goes through and the merged company has a larger enterprise value (estimated at $28B-$30B by BTIG). However, depending on the remaining debt load after DISH’s investment, it still seems like a reasonable objective. Having a public market valuation for T-Mobile also makes DT’s decision about what share of the company DISH would receive a lot more transparent.
Of course, this new development also makes it rather more reasonable to regard a potential DISH bid for LightSquared as another bluff by Ergen, or at the very least a far less attractive fallback option (and if you think a deal might still be done with LightSquared as well as T-Mobile, note that DT is currently embroiled in its own LightSquared-like ATC scandal in India, with some of the original SkyTerra investors). It also confirms that DISH has moved on from its interest in Clearwire, and will most likely just look to cash in its sizeable profits (of up to $300M) on Clearwire’s debt when the Sprint merger eventually goes through.
UPDATE 2 (4/12): Clearwire has filed a proxy statement this evening, noting that it was approached by Party J, a strategic (i.e. non-financial) buyer, earlier this week with an offer to buy 5B MHzPOPs “in large markets” for $1.0B-$1.5B minus the NPV of the associated lease payments. Given the NPV of Clearwire’s lease payments is $1.8B of which I’d guess at least two-thirds is in large markets, and 5B MHz POPs would be around half of the leased spectrum in these markets (assuming this is the top 100M POPs in the US), that would mean a deduction of $600M or more, leaving a net price of ~$400M-$900M.
Walt Piecyk at BTIG thinks that Party J might be Ergen once again and I tend to agree (perhaps this approach is through Echostar?). It would fit with the move on LightSquared last week as another effort to establish a potential backup to T-Mobile, by persuading Clearwire stakeholders to hold out for more money and reject the Sprint bid. Clearwire seems to be hinting that it will file for bankruptcy on June 1 if the Sprint bid is rejected and that would also provide Ergen with far more options in the event that he can’t pull off a deal with T-Mobile, because of his substantial holdings of Clearwire debt. However, given the difficult relationship between Sprint and DISH and the numerous challenges associated with LightSquared, both look far less attractive options than a deal with DT for DISH to invest in T-Mobile.
No I’m not talking about Intelsat’s current IPO! Although some might raise questions about the company’s debt levels, its also pretty clear that Intelsat’s mobility strategy and its high throughput Epic satellites are the envy of its FSS competitors. What I’m actually referring to is Row44, which went public at the end of January through a merger with Global Eagle, which had raised $190M in a blank check IPO. The end of year results from Row44 and Global Eagle have gone completed unreported, but were filed with the SEC last month, and highlighted just what a disastrous business Row44 really is.
In particular, as installations of the Southwest fleet neared completion, Row44′s revenues in Q4 dropped by 27% compared to Q3 (from $20.1M to $14.8M). Moreover, Row44 only generated total Internet connectivity revenues of $11.4M in 2012 while spending $19.6M on buying bandwidth from Hughes, and produced no revenues from its much ballyhooed content and portal services (despite spending $1.9M on video licensing fees).
In 2013, Row44′s satellite connectivity commitment to Hughes will go up to a minimum of $28M (and more likely well over $30M, because of additional commitments made in early 2013 to add coverage in Russia, and additional trans-Pacific coverage planned later this year). Row44 has also changed its deal with Southwest, so it now only receives fees for passengers using connectivity (between $5 and $6 per user, while Southwest charges $8 for the service), rather than Southwest paying for every boarded passenger under the original agreement, and as part of the new contract, Row44 is adding more capacity, apparently to counter passenger complaints about “slow or restricted services”.
At an investor conference on March 13, Global Eagle’s CFO suggested that paid take rates for other providers “range from high single digits to high teens” and that inferences could be drawn from that for Row44′s take rates on Southwest. Of course that is completely untrue: take rates for Gogo are around 5%, and Global Eagle itself said back in November that the targeted take rate on Southwest was 6.5% in 2014, so its hardly likely that the take rate is higher than that today. I therefore have to wonder if Global Eagle’s CFO actually understands this business at all.
Indeed, the company seems to have a hard time predicting the outlook for its business even in the very short term: this March 13 presentation indicated that the 2012 adjusted EBITDA from Row44 and AIA respectively was -$26M and +$18M respectively, whereas on November 27, 2012, with just one month left in the year, Global Eagle forecast that the full year adjusted EBITDA results for Row44 and AIA would be -$25M and +$22.3M respectively.
If we look forward to 2013, then it seems certain that Row44′s revenues will decline sharply, because of the slowdown in equipment installations (from $61M of equipment revenues in 2012 to ~$35M in 2013, and potentially to only $20M in 2014, based on Row44′s current business plan). More importantly, the company is set to make another significant loss on provision of connectivity services: I estimate $20M-$25M in revenues, depending on the take rates that Southwest achieves, compared to connectivity costs of well over $30M and more likely close to $40M (just in payments to Hughes, ignoring Row44′s own operational costs). In addition, content revenue is still minimal (Global Eagle described the product as “brand new” in mid March), with a very limited selection available, and by my estimate content and portal revenues will be no more than ~$5M this year.
In the longer term, Row44′s new deal with Southwest has locked the airline into a deeply unfavorable competitive position vis-a-vis JetBlue, who intend to offer Internet access for free. Southwest can’t possibly do the same, if they have to pay Row44 at least $5 for every passenger who uses the service, despite the two airlines competing very actively on other passenger amenities (like free checked bags). Moreover, if Row44 is ever to break even, it may have to cut back on the amount of capacity it buys from Hughes (rather than boosting capacity as Southwest currently plans), making Southwest’s Internet service even less attractive compared to JetBlue, which uses much cheaper Ka-band capacity.
In recent days, we’ve seen yet another report predicting rapid growth for in-flight connectivity deployment and revenues. However, none of these reports have got to grips with the issue of what services can be profitable for providers but still affordable for the airlines. Of course, if there’s one lesson to be learned from the Connexion-by-Boeing debacle, its that you can’t just assume companies will be able to continue providing service at an enormous loss indefinitely. After scraping through 2012, raising money at effective interest rates of up to 421%, Row44 has escaped for the time being by capturing Global Eagle’s cash balance. Perhaps unsurprisingly, given its management’s apparently tenuous connection to reality, Global Eagle now intends to “use its balance sheet” to pursue consolidation of the in-flight connectivity business, which might provide some relief from Row44′s current unsustainable business model, but on the other hand may simply drag down other companies in the sector.
We’ll be publishing our own detailed report on the in-flight connectivity business next month, which takes a very different approach to the analyses we’ve seen so far: instead of simply projecting how many planes might be fitted out with each technology, we’ll look at both the revenue and cost base of the various IFC providers, and discuss which of them may be able to find a sustainable long term business model.