08.26.26
Posted in Amazon, AST SpaceMobile, Financials, Globalstar, Iridium, SpaceX, Spectrum, ViaSat at 4:27 pm by timfarrar
On August 13, RocketLab filed the S-4 registration statement for the acquisition of Iridium, which just like Amazon and Globalstar a couple of weeks earlier, set out details of the process that led to the deal being struck.
In this case RocketLab and Iridium began discussions on December 1, 2025, followed by a call between the CEOs on December 15. Further meetings continued in January and February and RocketLab began due diligence in March. After the Amazon acquisition of Globalstar was announced on April 14, the next day RocketLab delivered its first offer of $42.50 in RocketLab shares. An updated offer of $52 per share ($15 in cash and $37 in RocketLab shares) was submitted on June 3 and this was updated further to $26 per share in cash and $26 in RocketLab shares on June 22, before being finalized at $54 (again 50/50 cash and shares) the next day. The dates on which RocketLab began discussions with Iridium are consistent with my assumption that RocketLab was Globalstar’s Party A that made an initial bid but pulled out of the process with Globalstar on December 4.
What is remarkable about the deal is how Iridium was able to push RocketLab’s offer up by over 25% despite there being relatively little competition for Iridium’s assets. The registration statement identifies three parties A, B and C as potential rival bidders, but the only one of these that made a serious offer was Party A, which had initially began meeting with Iridium in November 2025 and conducted due diligence in parallel with RocketLab, before submitting an initial all cash offer of $41 to $45 per share on June 2, which it refused to raise further.
After the Amazon-Globalstar announcement, Iridium’s advisors at Evercore reached out to 10 other potential strategic counterparties of which 4 signed confidentiality agreements but only one (Party B) entered into formal due diligence on May 13 and terminated this two weeks later without making an offer. The only other identified party (Party C), which had not been the subject of Evercore’s outreach, had their CEO reach out to Iridium’s CEO on May 7, but on May 12 said it would not be submitting a proposal to acquire Iridium.
Iridium and Evercore clearly knew at Satellite 2026 about rumors that the Globalstar deal was coming and appear to have cleverly extended the process so that this announcement would inevitably lead to speculation about an Iridium sale and drive up the share price. They also played off the certainty of the cash offer from Party A (without telling RocketLab how low this was) to get a much higher share of cash (“value certainty”) in the RocketLab offer.
So who are Party A, B and C? Party A appears to have been a private equity firm, given the lengthy and detailed due diligence and the emphasis on an all cash offer (including cash settlement of Iridium’s employee equity incentives), as well as the refusal to improve the offer based on Party A’s belief “that Iridium Common Stock was trading at elevated levels amid market speculation about a potential strategic transaction” (i.e. Party A was not a “strategic” bidder).
Party B was indicated to “require a strategic partner with which to pursue an acquisition of Iridium” which makes it clear that Party B wasn’t Amazon as some might have assumed. The most plausible “strategic counterparty” in this category is AST SpaceMobile, which would have needed backing from one or more telcos in order to make a viable bid for Iridium.
And Party C is most likely Viasat, which wouldn’t have been in a position to make a bid (and for this reason, as indicated in the registration statement, would probably not have been a “strategic counterparty” that Evercore engaged with), but would have wanted to understand more about what was happening with this key competitor.
So what does this tell us? Firstly, that neither Amazon nor SpaceX were interested in bidding for Iridium. And secondly, that AST isn’t well positioned to make a large cash bid for spectrum (either from Grain or Viasat) without backing from a telco partner. That suggests that the current frantic speculation about a potential bidding war between these companies for Viasat’s spectrum may be misplaced.
Viasat’s L-band spectrum is certainly more attractive than Iridium’s more limited amount of spectrum for companies (unlike RocketLab) that are focused on a broadband D2D deployment. But one might conclude that SpaceX and Amazon want to focus on building their satellite networks rather than paying billions for more spectrum in the immediate future. And then they can see whether or not Equatys is able to move forward to deploy its own LEO D2D constellation.
However, many spectrum speculators would now be deeply disappointed if Viasat actually does commit large sums of money to building a LEO D2D network and tries to compete head-on with SpaceX, Amazon and AST.
Permalink
08.10.26
Posted in Broadband, D2D, Operators, Services, SpaceX, T-Mobile at 9:47 am by timfarrar
As I pointed out in a Wednesday interview on TITV, the most startling claim in last week’s SpaceX results call was Elon Musk’s assertion that “probably a year from now, we will be doing at least 1 flight a day [of Starship], possibly more”. A smart Bloomberg piece by Liam Denning on Thursday highlighted that “Musk is on an accelerating treadmill of prediction” and while “moon factories may be taken seriously-not-literally by investors”, both robotaxis and Starship launches are “quantified and verifiable” so “Musk is on the hook to deliver ever more and, crucially, ever more quickly”.
To date, daily (or even hourly!) Starship launches have been most easily been explained by the supposedly unlimited demand for orbital data centers. But those are dependent on two things: 1) a Starship launchpad suitable for sun-synchronous orbits (for which land is now being acquired in Louisiana) and 2) new chips made at Terafab that are suitable for operating at much higher temperatures (this is in order to maximize radiative cooling in space, since increasing the operating temperature by 100°C will shrink the required radiator size by ~70%). However, neither the launchpad nor the new Terafab chips will be ready until 2030 or beyond, so they won’t contribute to Starship demand next year.
That leaves Starlink as the only realistic source of demand for frequent Starship launches next year and so Musk has been on a rant for much of the weekend on X, seeking to justify demand for 100K+ Starlink V3 satellites (since 365 launches of 60 Starlink satellites each year, times a five year lifetime would be ~110K satellites on orbit) as opposed to Gwynne Shotwell’s far more rational forecast in March that “I don’t think we’ll have more than 15 or 20,000 Starlink satellites” (she instead leaned on the FCC application for “up to a million AI satellites” as the primary driver of Starship demand). Musk has been egged on by cheerleaders such as ARK and Mach33 fawning over the supposed 100x increase in bandwidth (although the latter are at least aware enough to acknowledge that the space industry is now “replete with grifters”).
But remember that current Starlink V2 mini satellites can each serve around 2000 consumers globally, and even if the provisioning rate is doubled, each Starlink V3 satellite should be able to serve 10,000 consumers. So 15K-20K V3 satellites would be enough for 150M-200M customers (fewer if some satellites are devoted to D2D), whereas 100K V3 satellites would only be justified by Starlink acquiring a billion fixed broadband customers, which is more than the total available worldwide market (today there are about 1.6B fixed broadband users, but nearly half of those are in China and Russia).
This problem has forced Elon Musk to make ever wilder claims about demand coming from an “orders of magnitude” increase in demand from “AI and robotics” and subsequently that “AI agentic Internet traffic will obviously VASTLY exceed human usage”, not to mention that “All cars will have Starlink in the future”. First he started with “I would expect Starlink to reach at least 25% market share outside of China…It’s not out of the question that Starlink carries more than 50% of Internet traffic long-term, which would probably be over a trillion/year”, then moved on to “Future versions of our satellites may exceed 50X the throughput of a V2″ and by late Sunday night he was claiming that “It’s possible that Starlink may end up doing >90% of IP traffic, even if competitors 10X their bandwidth”. All I can say is, don’t do drugs kids!
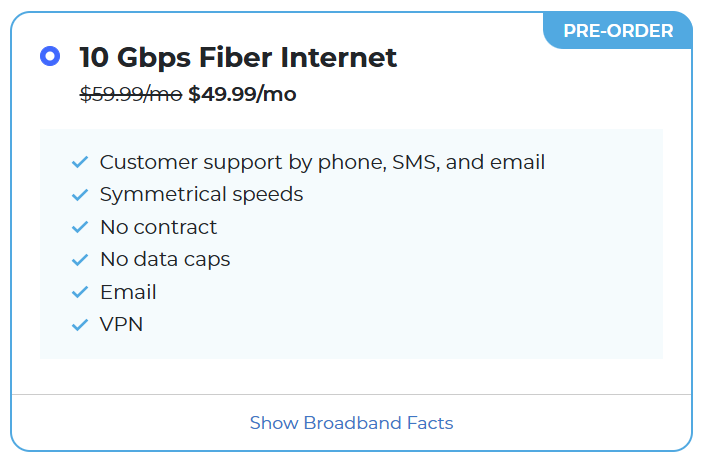
Of course this is total nonsense: except for a very few outliers (such as military users) high bandwidth customers use fiber today and the cost of increased provisioning once fiber is already installed is minimal, in the US the extra IP transit bandwidth if residential customers used 10 times more bandwidth (say 5Tbytes per month instead of 500Gbytes per month) would be about $1-$2 per subscriber per month. Where available, residential fiber users can already get symmetric 10Gbps connections for as little as $50 per month (this example is from Sonic). For comparison, Starlink’s existing community gateways, capable of the same throughput, were reportedly priced at $75,000 per Gbps per month.
Starlink’s fixed broadband service is and will remain inferior to fiber, not least because of constraints on uplink speed, and unlike fiber, Starlink will need to invest huge sums of money in these new satellites if customer usage increases by an order of magnitude in peak demand areas like the US. SpaceX’s S-1 indicates that there has been reduction in manufacturing cost per Gbps of satellite capacity of 3 times from V1 to V2 mini and the expected reduction is 9 times from V1 to V3, but this implies that the V3 satellites will cost around $2M each, to which the cost of launch needs to be added. Thus, even taking an optimistic view of Starship launch costs, 100K Starlink V3 satellites will require a capital investment of well over $200B and most likely $300B+.
Musk also fails to distinguish between fixed and mobile use cases: yes you may want to access AI via your phone, but Starlink Mobile’s D2D (i.e. satellite) service will be far inferior to terrestrial cellular networks in urban and suburban areas (especially indoors), which SpaceX acknowledged by asserting that they now intend to build out a terrestrial small cell network in the US because AT&T, Verizon and T-Mobile have refused to offer an MVNO deal. Ironically, one of the triggers that prompted Musk to make his litany of exaggerated claims this weekend may have been the FT’s interview with T-Mobile’s CEO, which claimed that “The threat posed to mobile operators from satellite companies such as Starlink has been exaggerated”, as the fight over pricing with T-Mobile becomes ever more tense (I expect Starlink’s next moves may include a deal with the cable companies and an acquisition of EchoStar’s CBRS spectrum).
So where does that leave us? Most likely we will never need to find out if there is demand for daily Starship launches next year, because SpaceX won’t actually achieve that goal: a launch every 1-2 weeks by mid year is plausible, but many of those launches will need to be devoted to Starlink Mobile not V3 broadband.
However, a key signpost will be how much manufacturing capacity SpaceX builds out for Starlink terminals: the plan is to double capacity in Bastrop TX this year (while apparently closing down production in El Segundo CA), implying that SpaceX will make around 12M-13M terminals this year and have a run rate of around 300K terminals per week by the end of the year. Unless production increases further, that’s only enough to add about 2M customers per quarter, after allowing for churn. But even to believe claims that Starlink could launch as many as 4000 V3 satellites next year (enough for ~40M net adds but only 2 launches a week on average), Starlink would have to increase production to about 1M terminals per week over the course of next year.
Permalink
08.05.26
Posted in Amazon, AST SpaceMobile, D2D, Globalstar, Operators, Spectrum, T-Mobile, ViaSat at 1:30 pm by timfarrar
Last Friday, Amazon filed the draft prospectus for the acquisition of Globalstar which sets out the background of the merger, including details of the process that Globalstar ran in 2025 and early 2026 that resulted in the Amazon deal.
Globalstar and Amazon began meeting between March and September 2025 about “a potential strategic collaboration”. Amazon signed an NDA on September 12 and on October 16 submitted an initial price indication of $47.50 per Globalstar share in cash (~$6B). An updated bid of $65 in Amazon stock (or $75 in cash for public shareholders) was submitted on November 12, and then updated to $70 per share in Amazon stock on November 18. Finally on December 1, this was revised to $90 per share in cash or $70 in Amazon stock (later increased to $75), with a maximum of 40% of the consideration in cash, and Globalstar signed an exclusivity agreement on December 6. Although exclusivity expired briefly over the holidays, it was subsequently renewed and extended repeatedly to allow for finalization of the arrangements between Amazon and Apple and the deal was finally announced on April 14.
More intriguingly, the prospectus identifies three other unnamed Parties A, B and C, in addition to Amazon, that made formal or informal bids during the process:
Party A met with Globalstar “from time to time to discuss, among other things, Globalstar’s business and a potential strategic transaction involving Party A and Globalstar” between February and June 2025, and began due diligence on the company in July, making an initial verbal offer in late August and then a formal share-based offer of $4.3B-$5.7B on October 17 (plus some contingent value rights for “future monetization of certain spectrum licenses”). An updated offer of $65 to $75 per share was submitted on November 12 based on equal parts cash and stock (with the stock valued at Party A’s 60 day VWAP), but Party A declined to raise its offer further on December 4, “including because Party A and Customer [i.e. Apple] had not reached mutual agreement with respect to a post-closing commercial arrangement”.
Party B was first contacted by Globalstar’s financial advisers on July 24 and met with Globalstar over the following month to discuss a potential transaction. Party B began due diligence on September 1 and continued through November, submitting a verbal indication of an all-cash deal at $5B-$6B on October 6, followed by a written update on November 14, valuing Globalstar at $9.5B, “less net debt and any obligations owed to Customer (the terms of which were not specified), consisting of $3B in Party B stock, $3B in cash, and the balance in a contingent value right based on the potential sale or monetization of certain terrestrial spectrum assets of Globalstar.” However, Globalstar advised Party B that its CVR-based offer was not competitive and after signing an exclusivity agreement with Amazon, ignored attempts by Party B to reach out again in January 2026.
Party C was first contacted by Globalstar’s financial advisers between August 13 and 20, and on August 21 signed an NDA (which unlike all the other NDAs signed with potential acquirers in that period did not include a “standstill” provision). In mid-September, Globalstar noted that there was “uncertainty regarding Customer and Party C reaching a mutually acceptable post-closing commercial arrangement” and Party C submitted an indication of interest at $4B-$5B on September 23. Party C informed Globalstar’s representatives “that Party C believed that the value of any stock proposed as merger consideration would likely appreciate” and that “Party C was open to pursuing multiple alternative structures, including an acquisition of 100% of the equity of Globalstar, a purchase of spectrum assets or a purchase of Globalstar’s interest in its partnership with Customer”. Party C submitted an updated indicative bid of $8B on October 6, consisting of 50% cash and 50% in Party C stock, with an expectation that all the stock would go to Thermo. However, shortly thereafter, Apple advised Globalstar that “Party C had not engaged in discussions with Customer in recent weeks”.
Then, on October 17, Party C indicated that they were “potentially interested in a transaction that valued Globalstar in the ‘mid teens billions’ (based on Party C’s assertions that the value of any Party C stock proposed as merger consideration would likely appreciate), but that Party C required additional time to discuss a post-closing commercial arrangement with Customer before it could make an updated proposal.” However, by October 29, Party C reported that “Party C and Customer had not progressed discussions with respect to post-closing commercial arrangements between Party C and Customer” and Apple told Globalstar that Apple “thought it was uncertain that a commercial arrangement between Customer and Party C could be reached on terms acceptable to both parties based on Party C’s current proposals.” A November 11 letter from Party C indicated that Party C “remained interested…but required additional time to obtain Customer’s support for a Potential Transaction between Party C and Globalstar and, if Customer was supportive, align with Customer on the terms of a commercial agreement and negotiate the relevant documents.” However, on December 22, Globalstar was told that “Party C was unable to further pursue a Potential Transaction, including because Party C and Customer had not reached mutual agreement with respect to a post-closing commercial arrangement.”
So who are Parties A, B and C? It’s pretty clear that Party C is SpaceX given that the structure they proposed is very similar to that with EchoStar: 50/50 stock/cash, with an expectation that the stock “would likely appreciate”. It is notable that a major barrier to Party C’s bid was the tense negotiations and resulting lack of any commercial agreement with Apple. This confirms that what I posted last September about the pressure SpaceX was putting on Apple was exactly right, rather than “pretty much everything is wrong” as Elon Musk posted in an attempt to head off further reporting on this issue.
Party B appears to be T-Mobile or Deutsche Telekom, which as I’ve noted previously, were involved in the process, after deciding not to pay up for EchoStar’s AWS-4 last summer, but didn’t make a particularly serious attempt to win. The timing also fits with T-Mobile dropping out of the bidding for AWS-4 in July and commencing due diligence at the beginning of September once it became clear that SpaceX was likely to buy EchoStar’s spectrum.
And then Party A appears to be either RocketLab or AST: the giveaway here is the 60 day VWAP between mid September and mid November 2025, which covers a period when the share price of both companies surged to a peak before falling back. In my view it was probably the former, since RocketLab would already have been meeting with Globalstar between February and June 2025 to discuss “other things”, namely the delayed replacement satellites. And RocketLab is less likely than AST to have been interested in retaining “certain spectrum licenses” (presumably terrestrial Band 53 rights).
So what does that imply for the universe of potential spectrum bidders for Viasat’s L-band, as investors have asked me on numerous occasions in recent weeks? There’s little chance that AST and Viasat could reach a meeting of minds over L-band, and RocketLab is off the table after the recent Iridium deal. SpaceX doesn’t need more MSS spectrum right now (and certainly not Viasat’s spectrum which is mostly outside the US): if anything SpaceX will be buying US terrestrial spectrum, most plausibly EchoStar’s CBRS spectrum to facilitate a potential cable partnership for Starlink Mobile V2.
Amongst Parties A, B and C, we are therefore left with T-Mobile/Deutsche Telekom, but after saying on the last earnings call about D2D that “having worked closely with satellite over the last 4 years, we’re just not seeing that incremental differentiation” it appears unlikely that T-Mobile would be interested in investing in satellite spectrum. And does Amazon want to acquire more D2D spectrum right now, especially when it has so much on its plate getting the broadband system into orbit and completing the Globalstar acquisition?
As a result, I think bidders for Viasat’s spectrum are likely to be scarce or non-existent, and despite the challenges that Equatys faces after the loss of RocketLab, it looks like Viasat will continue trying to build a D2D constellation, rather than selling its spectrum to others. Or as Viasat said on the results call last night, “what we’re holding up for is to have the next announcement, which really would be about the Equatys purchase of its initial satellite constellation.”
Permalink