08.26.26
Posted in Amazon, AST SpaceMobile, Financials, Globalstar, Iridium, SpaceX, Spectrum, ViaSat at 4:27 pm by timfarrar
On August 13, RocketLab filed the S-4 registration statement for the acquisition of Iridium, which just like Amazon and Globalstar a couple of weeks earlier, set out details of the process that led to the deal being struck.
In this case RocketLab and Iridium began discussions on December 1, 2025, followed by a call between the CEOs on December 15. Further meetings continued in January and February and RocketLab began due diligence in March. After the Amazon acquisition of Globalstar was announced on April 14, the next day RocketLab delivered its first offer of $42.50 in RocketLab shares. An updated offer of $52 per share ($15 in cash and $37 in RocketLab shares) was submitted on June 3 and this was updated further to $26 per share in cash and $26 in RocketLab shares on June 22, before being finalized at $54 (again 50/50 cash and shares) the next day. The dates on which RocketLab began discussions with Iridium are consistent with my assumption that RocketLab was Globalstar’s Party A that made an initial bid but pulled out of the process with Globalstar on December 4.
What is remarkable about the deal is how Iridium was able to push RocketLab’s offer up by over 25% despite there being relatively little competition for Iridium’s assets. The registration statement identifies three parties A, B and C as potential rival bidders, but the only one of these that made a serious offer was Party A, which had initially began meeting with Iridium in November 2025 and conducted due diligence in parallel with RocketLab, before submitting an initial all cash offer of $41 to $45 per share on June 2, which it refused to raise further.
After the Amazon-Globalstar announcement, Iridium’s advisors at Evercore reached out to 10 other potential strategic counterparties of which 4 signed confidentiality agreements but only one (Party B) entered into formal due diligence on May 13 and terminated this two weeks later without making an offer. The only other identified party (Party C), which had not been the subject of Evercore’s outreach, had their CEO reach out to Iridium’s CEO on May 7, but on May 12 said it would not be submitting a proposal to acquire Iridium.
Iridium and Evercore clearly knew at Satellite 2026 about rumors that the Globalstar deal was coming and appear to have cleverly extended the process so that this announcement would inevitably lead to speculation about an Iridium sale and drive up the share price. They also played off the certainty of the cash offer from Party A (without telling RocketLab how low this was) to get a much higher share of cash (“value certainty”) in the RocketLab offer.
So who are Party A, B and C? Party A appears to have been a private equity firm, given the lengthy and detailed due diligence and the emphasis on an all cash offer (including cash settlement of Iridium’s employee equity incentives), as well as the refusal to improve the offer based on Party A’s belief “that Iridium Common Stock was trading at elevated levels amid market speculation about a potential strategic transaction” (i.e. Party A was not a “strategic” bidder).
[EDIT 9/17] We now understand from multiple sources at WSBW that Party A was Amazon, which wanted to buy both Globalstar and Iridium and combine the two companies, although Amazon’s behavior was perplexing, allowing the Iridium negotiations to run on beyond the date on which the Globalstar acquisition was announced, rather than setting a firm deadline, and then seemingly being surprised that this announcement caused Iridium’s share price to rise above the value that Amazon was prepared to pay.
Party B was indicated to “require a strategic partner with which to pursue an acquisition of Iridium” which makes it clear that Party B wasn’t Amazon as some might have assumed. The most plausible “strategic counterparty” in this category is AST SpaceMobile, which would have needed backing from one or more telcos in order to make a viable bid for Iridium.
And Party C is most likely Viasat, which wouldn’t have been in a position to make a bid (and for this reason, as indicated in the registration statement, would probably not have been a “strategic counterparty” that Evercore engaged with), but would have wanted to understand more about what was happening with this key competitor.
So what does this tell us? Firstly, that neither Amazon nor SpaceX were interested in bidding for Iridium. And secondly, that AST isn’t well positioned to make a large cash bid for spectrum (either from Grain or Viasat) without backing from a telco partner. That suggests that the current frantic speculation about a potential bidding war between these companies for Viasat’s spectrum may be misplaced.
[EDIT 9/17] Amazon’s desire to acquire spectrum was greater than we assumed and it appears that Amazon felt this year may have represented the last chance to lock up one of the limited bands of global MSS spectrum that is available. After losing out on Iridium, Amazon might still be interested in securing additional spectrum from Viasat, and it would now not be a total surprise if Viasat received bids from other companies as well, if they take the same view that this is their last best chance to buy more MSS spectrum. Nevertheless, at this point in time, Viasat appears determined to move forward with the Equatys buildout, rather than pursuing a sale process, and has just committed $400M to the venture. Put another way, we suspect that Viasat’s asking price to abandon Equatys would be far greater than any potential spectrum buyer would be prepared to pay.
Viasat’s L-band spectrum is certainly more attractive than Iridium’s more limited amount of spectrum for companies (unlike RocketLab) that are focused on a broadband D2D deployment. But one might conclude that SpaceX and Amazon want to focus on building their satellite networks rather than paying billions for more spectrum in the immediate future. And then they can see whether or not Equatys is able to move forward to deploy its own LEO D2D constellation.
However, many spectrum speculators would now be deeply disappointed if Viasat actually does commit large sums of money to building a LEO D2D network and tries to compete head-on with SpaceX, Amazon and AST. [EDIT 9/17] And they would be even more disappointed if Viasat turns down sizable offers (which could be perhaps $6B-$10B) to buy its L-band spectrum.
Permalink
08.10.26
Posted in Broadband, D2D, Operators, Services, SpaceX, T-Mobile at 9:47 am by timfarrar
As I pointed out in a Wednesday interview on TITV, the most startling claim in last week’s SpaceX results call was Elon Musk’s assertion that “probably a year from now, we will be doing at least 1 flight a day [of Starship], possibly more”. A smart Bloomberg piece by Liam Denning on Thursday highlighted that “Musk is on an accelerating treadmill of prediction” and while “moon factories may be taken seriously-not-literally by investors”, both robotaxis and Starship launches are “quantified and verifiable” so “Musk is on the hook to deliver ever more and, crucially, ever more quickly”.
To date, daily (or even hourly!) Starship launches have been most easily been explained by the supposedly unlimited demand for orbital data centers. But those are dependent on two things: 1) a Starship launchpad suitable for sun-synchronous orbits (for which land is now being acquired in Louisiana) and 2) new chips made at Terafab that are suitable for operating at much higher temperatures (this is in order to maximize radiative cooling in space, since increasing the operating temperature by 100°C will shrink the required radiator size by ~70%). However, neither the launchpad nor the new Terafab chips will be ready until 2030 or beyond, so they won’t contribute to Starship demand next year.
That leaves Starlink as the only realistic source of demand for frequent Starship launches next year and so Musk has been on a rant for much of the weekend on X, seeking to justify demand for 100K+ Starlink V3 satellites (since 365 launches of 60 Starlink satellites each year, times a five year lifetime would be ~110K satellites on orbit) as opposed to Gwynne Shotwell’s far more rational forecast in March that “I don’t think we’ll have more than 15 or 20,000 Starlink satellites” (she instead leaned on the FCC application for “up to a million AI satellites” as the primary driver of Starship demand). Musk has been egged on by cheerleaders such as ARK and Mach33 fawning over the supposed 100x increase in bandwidth (although the latter are at least aware enough to acknowledge that the space industry is now “replete with grifters”).
But remember that current Starlink V2 mini satellites can each serve around 2000 consumers globally, and even if the provisioning rate is doubled, each Starlink V3 satellite should be able to serve 10,000 consumers. So 15K-20K V3 satellites would be enough for 150M-200M customers (fewer if some satellites are devoted to D2D), whereas 100K V3 satellites would only be justified by Starlink acquiring a billion fixed broadband customers, which is more than the total available worldwide market (today there are about 1.6B fixed broadband users, but nearly half of those are in China and Russia).
This problem has forced Elon Musk to make ever wilder claims about demand coming from an “orders of magnitude” increase in demand from “AI and robotics” and subsequently that “AI agentic Internet traffic will obviously VASTLY exceed human usage”, not to mention that “All cars will have Starlink in the future”. First he started with “I would expect Starlink to reach at least 25% market share outside of China…It’s not out of the question that Starlink carries more than 50% of Internet traffic long-term, which would probably be over a trillion/year”, then moved on to “Future versions of our satellites may exceed 50X the throughput of a V2″ and by late Sunday night he was claiming that “It’s possible that Starlink may end up doing >90% of IP traffic, even if competitors 10X their bandwidth”. All I can say is, don’t do drugs kids!
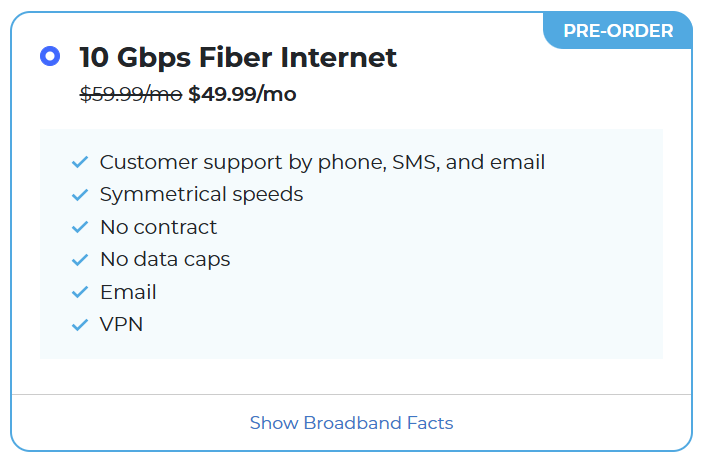
Of course this is total nonsense: except for a very few outliers (such as military users) high bandwidth customers use fiber today and the cost of increased provisioning once fiber is already installed is minimal, in the US the extra IP transit bandwidth if residential customers used 10 times more bandwidth (say 5Tbytes per month instead of 500Gbytes per month) would be about $1-$2 per subscriber per month. Where available, residential fiber users can already get symmetric 10Gbps connections for as little as $50 per month (this example is from Sonic). For comparison, Starlink’s existing community gateways, capable of the same throughput, were reportedly priced at $75,000 per Gbps per month.
Starlink’s fixed broadband service is and will remain inferior to fiber, not least because of constraints on uplink speed, and unlike fiber, Starlink will need to invest huge sums of money in these new satellites if customer usage increases by an order of magnitude in peak demand areas like the US. SpaceX’s S-1 indicates that there has been reduction in manufacturing cost per Gbps of satellite capacity of 3 times from V1 to V2 mini and the expected reduction is 9 times from V1 to V3, but this implies that the V3 satellites will cost around $2M each, to which the cost of launch needs to be added. Thus, even taking an optimistic view of Starship launch costs, 100K Starlink V3 satellites will require a capital investment of well over $200B and most likely $300B+.
Musk also fails to distinguish between fixed and mobile use cases: yes you may want to access AI via your phone, but Starlink Mobile’s D2D (i.e. satellite) service will be far inferior to terrestrial cellular networks in urban and suburban areas (especially indoors), which SpaceX acknowledged by asserting that they now intend to build out a terrestrial small cell network in the US because AT&T, Verizon and T-Mobile have refused to offer an MVNO deal. Ironically, one of the triggers that prompted Musk to make his litany of exaggerated claims this weekend may have been the FT’s interview with T-Mobile’s CEO, which claimed that “The threat posed to mobile operators from satellite companies such as Starlink has been exaggerated”, as the fight over pricing with T-Mobile becomes ever more tense (I expect Starlink’s next moves may include a deal with the cable companies and an acquisition of EchoStar’s CBRS spectrum).
So where does that leave us? Most likely we will never need to find out if there is demand for daily Starship launches next year, because SpaceX won’t actually achieve that goal: a launch every 1-2 weeks by mid year is plausible, but many of those launches will need to be devoted to Starlink Mobile not V3 broadband.
However, a key signpost will be how much manufacturing capacity SpaceX builds out for Starlink terminals: the plan is to double capacity in Bastrop TX this year (while apparently closing down production in El Segundo CA), implying that SpaceX will make around 12M-13M terminals this year and have a run rate of around 300K terminals per week by the end of the year. Unless production increases further, that’s only enough to add about 2M customers per quarter, after allowing for churn. But even to believe claims that Starlink could launch as many as 4000 V3 satellites next year (enough for ~40M net adds but only 2 launches a week on average), Starlink would have to increase production to about 1M terminals per week over the course of next year.
Permalink
07.23.26
Posted in Broadband, D2D, Financials, Operators, SpaceX, Spectrum at 1:53 pm by timfarrar
I just released my new 100+ page Starlink profile and forecasts, which you can order here. It contains detailed forecasts through 2030 of the consumer, enterprise, government and D2D businesses as well as analysis of Starlink’s technology and regulatory progress.
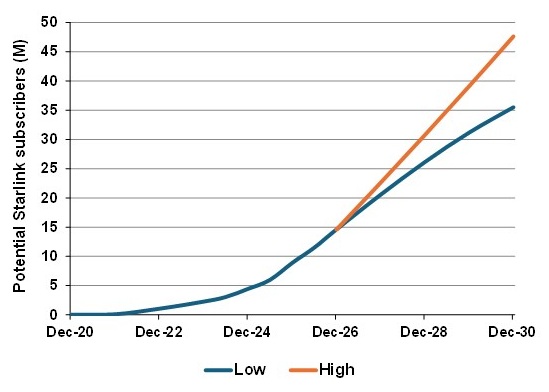
It has been interesting to compare my numbers with those published by various Wall St analysts, and understand the reasons for these differences. The range of forecasts for the connectivity segment in the reports I’ve seen is pretty wide, but all are a lot higher than my projection of $48B total revs and 46M consumer subs in 2030, with total connectivity revenues and consumer subs as follows:
Deutsche Bank: $72B revs, 82M subs
Moffett Nathanson: $73B revs, 70M subs
RBC: $101B revs, 100M+ subs
Morgan Stanley: $121B, 116M subs.
Unsurprisingly, the most similar forecast to mine is the one from Moffett Nathanson, as Craig Moffett and I share many of the same views about Starlink’s D2D market constraints, and used very similar methods to forecast the consumer market opportunity. The main discrepancy is in the enterprise and government sector, where I’ve broken down the revenue by enterprise, maritime, aviation and government in more detail based on Starlink’s disclosures about pricing and penetration. Deutsche Bank takes a more optimistic view of Starlink’s ability to expand consumer penetration in developing countries via aggressive reductions in ARPU, while also being much more optimistic about enterprise, government and mobility demand. And then RBC and Morgan Stanley take even more optimistic views about demand in all three parts of Starlink’s connectivity business.
One area seemingly missing from most analyst reports is an assessment of how terminal revenues and costs limit the scope for revenue growth (equipment generated $1.5B in revenue last year but is a one-off not a recurring revenue source) and price reductions for end customers (terminals cost an average of over $300 to produce last year). So I end up with higher consumer ARPUs (and slower growth) than many other forecasts, because the need for terminal subsidies (and higher ARPUs to compensate) will constrain demand in developing countries.
The biggest debate is what comes next in mobility. As I’ve noted before, Starlink Mobile’s wholesale ARPUs are far lower than most analysts expect, i.e. tens of cents rather than multiple dollars per customer (of whom less than 10% are active), with partner access fees (effectively minimum commitments) bridging the gap to last year’s reported revenues.
There’s still an opportunity to gain several billion dollars of annual revenue from the Starlink Mobile V2 constellation, if Starlink continues to offer wholesale service to MNOs at a low price (I estimate the effective wholesale capacity price could be under $2 per Gbyte on V2). But that won’t provide a return on $20B of spectrum purchased from EchoStar. And the JV between the US MNOs will try to drive a hard bargain on price by playing off the satellite D2D providers against one another (though AST and Amazon’s offerings are unlikely to match up to what Starlink Mobile V2 will deliver in 2028).
So with MNOs wisely refusing to give Starlink an MVNO deal (thereby retaining their competitive advantage in bundled fixed and mobile services), what is SpaceX going to do? It looks like a small cell plan might be part of the answer: Starlink could copy Charlie Ergen’s plan for Clearwire back in 2013, which involved adding small cells to rooftop satellite (TV) dishes, and speculation is now mounting about perhaps even adding small cells to Cybercabs. I’ve also heard rumors that Samsung might even be building a phone that could carry the Starlink Mobile brand.
One potential source of spectrum for a terrestrial network would be to buy EchoStar’s CBRS spectrum, which is a lot more usable than upper C-band spectrum that won’t be available until 2031 (and isn’t compatible with current phones). And perhaps a deal with one or more cable companies that already use CBRS could be on the table: Starlink broadband could then potentially provide an out of footprint competitive solution that is analogous to FWA for the telcos. However, it remains to be seen how Starlink could address the in-building terrestrial network advantages that AT&T was so keen to highlight “in the stadium…in the hospital…in the high-rise building”.
I pointed out in a recent paper for WIA that D2D complements terrestrial wireless coverage rather than replacing it, and will mostly be just a fallback option for remote and emergency use. So I don’t believe that Starlink can realistically hope to capture a sizeable part of the US wireless market with a D2D-led service, even if this was coupled with small cell coverage, unless it gained access to a terrestrial wireless network with a national footprint. And at the end of the day, while rattling the cage of the telcos may keep analysts and investors on the edge of their seats, SpaceX is all about access to space and the company’s prospects will ride (or die) on Starship.
Permalink
06.26.26
Posted in D2D, Financials, SpaceX, Spectrum, T-Mobile at 8:28 am by timfarrar
Since the SpaceX IPO earlier this month, speculation about SpaceX entering the mobile market has reached fever pitch, most recently in an FT article that cites comments made by Gwynne Shotwell to investors during the IPO roadshow. And of course we’ll hear imminently about the results of FCC Auction 113, where SpaceX is one of the bidders, and some analysts have been suggesting that SpaceX will buy much or all of the $3.5B in spectrum that was sold, not just the two unpaired licenses that SpaceX definitely need for their Band 70 offering (and which only sold for $10.5M).
But what is not being talked about is the context of a knife fight behind the scenes between SpaceX and T-Mobile over what T-Mobile will pay for the T-Satellite service after exclusivity expires next month. Because SpaceX was desperate to secure a launch partner and pre-empt Apple’s announcement with Globalstar back in August 2022, the current contract is reportedly only valued at “about $100M” in total since 2022, which means T-Mobile is likely only paying a few million dollars per month for the service. That’s only of order $1-$2 per monthly active user, when less than 10% of T-Mobile customers with T-Satellite included in their plan make use of the service in a given month. Or put another way, about $0.10 per month for each customer with access to the service.
But late last year, when SpaceX looked like it was going to come up short of Elon Musk’s 2025 projection of $15.5B in revenues, it seems the company booked an incremental $632M in (deferred) Starlink Mobile revenues so SpaceX would come close to Musk’s target (SpaceX’s actual reported revenue last year, excluding xAI, was $15.473B). That’s far above the current runrate reported for Starlink Mobile of $85M in 2026Q1.
So now, in order to show growth in 2026, SpaceX needs vastly increased revenues from T-Mobile (5-10 times the current level), when (based on the 2026Q1 runrate) T-Mobile is seemingly paying much less than SpaceX’s other MNO partners. As an example, I understand Rogers in Canada has suggested it might end up paying SpaceX up to CAD100M per year in a market which is about one tenth the size of the US. And we’ve seen numbers being floated like $500M per year for Starlink Mobile to provide service in Iran.
What is clear is that T-Mobile does not believe the service is worth that much, which is why they are being so vocal about how “most of the usage we’re seeing is in national parks” and “we’re seeing a lot less usage than we were originally thinking”, later quantified as “satellite usage is 0.0002% of our total network usage” and “pretty much, no one buys satellite stand-alone”. T-Mobile is even explicitly stating that “we expect that our exclusivity will end”.
T-Mobile is offering some carrots as well as sticks, promoting its new Super Broadband solution with Starlink as a backup for businesses. And of course in Europe, Deutsche Telekom’s support is going to be even more critical after the recent EU 2GHz proposal indicated that Starlink would not be allowed to utilize EchoStar’s spectrum license, even though that license will be extended to spring 2029.
But the proposed D2D joint venture with AT&T and Verizon aims to stop SpaceX from playing off the mobile operators against one another, and the operators have been united in their refusal to consider an MVNO relationship with SpaceX.
This is certainly the right time for the MNOs to hold the line on pricing of the Starlink Mobile service, as it will set an advantageous precedent for future D2D services if the wholesale cost for MNOs is in the low tens of cents per customer per month (an order of magnitude lower than the $2-$3/month assumed by many D2D proponents). And it seems hard to imagine SpaceX turning off the T-Satellite service before its own offering is ready in 2028 (though I wouldn’t completely dismiss the possibility of SpaceX completing the EchoStar transaction early and using some of the Band 70 spectrum on the current Starlink DTC satellites).
Are SpaceX’s current threats enough to change the mobile operators’ minds, even if SpaceX does buy more terrestrial spectrum? It’s always been expected that there will be some direct-to-consumer Starlink Mobile offering, most likely in the form of a smaller version of the Starlink Mini (a Starlink Nano?) operating in MSS frequencies with a much improved battery life, that you can connect to your phone via Bluetooth or WiFi. That’s very different to offering a fully fledged mobile service, when satellite links won’t deliver the data rates and inbuilding penetration expected from a terrestrial network.
But threats to buy a mobile operator or build a terrestrial mobile network seem like a paper tiger, which would do nothing to leverage SpaceX’s “core strengths” as set out in the S-1:
Global leadership in orbital launch services
Unrivaled satellite and connectivity platform across design, manufacturing, deployment, and operations
Truth-seeking AI model enhanced by real-time data
Extreme vertical integration enabling high velocity and superior cost efficiency at scale
Unique ability to scale new trillion-dollar markets across Space, Connectivity, and AI
Business models that are incredibly difficult to replicate
Our mission-driven culture and world-class talent.
So I look forward to seeing the revenues that SpaceX is able to report from Starlink Mobile in Q2 and Q3, and whether this is really a growth engine for the company in 2026, or if revenues actually fall from 2025 levels. If that’s the case then Starlink Mobile will presumably become another business (like Orbital Data Centers) where the hype is focused on what might be achieved with a next generation constellation in 2028 and beyond, while analysts continue seeking attention by playing up the possibility of SpaceX building, buying or leasing capacity for a fully fledged mobile service.
Permalink
06.04.26
Posted in Amazon, Broadband, Financials, SpaceX at 1:10 pm by timfarrar
One of the biggest uncertainties in the SpaceX IPO relates to the potential future growth of Starlink’s consumer business, which we discussed in detail in our 65 page report released on Tuesday this week. The most attention-grabbing claim from ARK Invest is that Starlink represents “a business without precedent” because even the early Starship launches of V3 satellites will produce twice as much revenue each year as it costs to manufacture and launch the satellites and acquire customers to fill them.
Those assertions (endorsed by Elon Musk) have led other analysts to predict that “SpaceX will disrupt [the] $1.6 trillion US communications industry” and justify a downgrade of AT&T, while Goldman Sachs is predicting that Starlink will generate $144B in revenue in 2030.
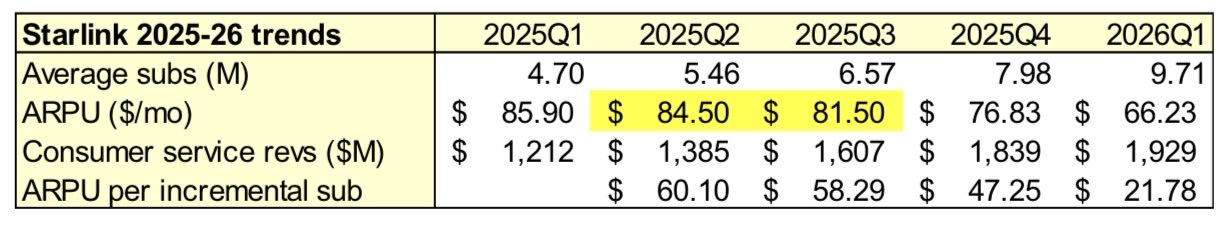
Starlink undoubtedly has a strong platform for growth, although you have to wonder why SpaceX suddenly decided to raise prices in the wake of a disappointing set of Q1 results, where ARPU dropped sharply, and incremental revenue per new subscriber was unsustainably low. That’s not the action of a company that’s looking to compete aggressively against terrestrial telcos and cable companies where multi-year “price lock” guarantees are all the rage.
Some have tried to explain away the price rises, as being “put in place because Starlink was having trouble coping with recent subscriber demand that was driven by price cuts”. But that doesn’t make much sense when Starlink net adds were lower in 2026Q1 (1.4M) than in 2025Q4 (~1.6M) and overall network performance improved continuously throughout 2025. Even potential terminal manufacturing constraints that were pointed out back in February will have been eased by the combination of fewer subscriber adds and increased production (which went from 170K per week at the end of 2025 to 200K per week as reported in the S-1).
[EDIT] And now Starlink has just announced it reached the 12M customer milestone, 111 days after the 10M milestone in February, which is a slightly slower growth rate than the 52 days from 9M to 10M and the 48 days from 8M to 9M customers.
Returning to the mad claims made by ARK, there are multiple errors in the assumptions, including that Starship will be able to launch 60 satellites right away when the roadshow presentation points out that will only be achieved “over time” and most importantly a dramatic underestimate of terminal costs, which at present are multiples of ARK’s assumed $100.
In their recent investor briefing, ST Microelectronics, who make the key chipsets for Starlink, said that “When you look at Ku band user terminal, I think that actually we’re going to soon reach a plateau” in the cost of their chips (which alone cost “a few tens of dollars” before the rest of the manufacturing takes place). At the end of the day, the cost of Starlink terminals is the key barrier to competing with terrestrial, not the cost of bandwidth.
Most egregious of all are ARK’s estimates of revenue per Tbps. If you look at Starlink’s $11.4B of revenues in 2025 and adjust for product revenues and Starshield/Starlink Mobile revenues that aren’t related to Starlink’s broadband business, then you get broadband service revenue in 2025 of about $15M per Tbps. With each extra Starlink V2 mini satellite adding capacity for ~2000 subs around the world, that’s about $62 of revenue per subscriber per month.
But Starlink’s current bandwidth provisioning will have to at least double if it is to compete fully for terrestrial subscribers. If we take the 10x increase in capacity per satellite on V3, but assume that provisioning doubles, that means each V3 satellite will add enough bandwidth to serve 10,000 new subscribers. At the same $62 per sub per month then that’s only $7.5M per Tbps launched. And if you want to compete with terrestrial then the incremental revenue per sub might only be $40 or so (under $5M per Tbps).
In contrast, ARK assumes that the initial Starship launches will generate $17M per Tbps (with a doubling of total system capacity) and $13M per Tbps if 10 times the current capacity is added, i.e. Starlink adds 6000Tbps, which would equate to winning another 100M subscribers with each generating an average of $65/month. That’s just not remotely credible (and incidentally explains why Musk’s daily or hourly launch tempo for Starship simply can’t be achieved based solely on Starlink demand).
Of course once you fix ARK’s underestimated costs and vastly inflated revenue assumptions then Starlink still looks like a very good business, with potential gross margins of around 60%. And Starlink should be able to capture a meaningful number of customers from terrestrial telcos in developed countries (about 100K per month in the US at the moment) if it does decide to price more aggressively at some point in the future. But don’t take these ridiculous assessments, which are being thrown out there to justify an IPO valuation of $1.75T, as saying anything about the reality of Starlink’s business potential and its impact on terrestrial telcos and cable companies. And ask yourself whether you believe Starlink’s next move will be to increase or decrease the price that customers are paying, especially when the prospect of competition from Amazon just moved even further into the future…
Permalink
06.02.26
Posted in Amazon, Broadband, Financials, Operators, SpaceX at 3:06 pm by timfarrar
I’ve been writing a lot about Starlink’s financials since the SpaceX S-1 came out almost two weeks ago and now I’ve just released my new 65 page report forecasting the opportunity for Starlink’s consumer business. The report pulls together the first detailed breakdown of how Starlink’s customers are distributed around the world, based on weekly monitoring of active terminals, and projects how the reported subscriber base and revenues will grow in the coming quarters and years by country and region.
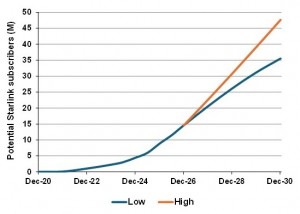
The report analyzes Starlink capacity density and terminal production and how these factors have constrained growth in recent years. It also discusses the limitations to future growth and how successfully Starlink will be able to compete with terrestrial alternatives in different countries. And the report compares the technology of Starlink and Amazon Leo to assess whether there is any realistic prospect of Amazon making significant inroads into Starlink’s subscriber base in the coming years.
Do you know the top 10 Starlink country markets (United States, Brazil, Canada, Argentina, Australia, Mexico, UK, Chile, France, Germany) and how many subscribers are in each country? Do you want to understand how Starlink’s growth in each country has changed since the price cuts in January, and why the price increases last month were so significant for Starlink’s future growth trajectory? You can even see why the various online estimates either significantly overestimate the subscriber base or get the regional distribution dramatically wrong.
This report will be followed up with a detailed set of projections for Starlink’s other business lines later this week, updating our previous company profile, and you can get both reports together at a discount. Or subscribe to the full research service and access our other reports from last year covering the D2D and professional satellite markets that Starlink competes in, plus all of our regular notes on key breaking news in the satellite sector for the next 12 months.
Permalink
03.24.26
Posted in Amazon, AST SpaceMobile, D2D, Globalstar, Lynk, Operators, Services, SpaceX, Spectrum, ViaSat at 5:43 pm by timfarrar
After more than 20 years, it looks like Jay Monroe has finally achieved his goal of selling Globalstar at a profit. In the coming days, I understand that the sale process initiated back in October will reach its conclusion, and Globalstar will be sold at something close to Jay’s asking price of $10B. And as I promised Jay in Paris last September, I’ll owe him an apology for ever doubting that he would be able to make money on his Globalstar investment.
Rumors have been swirling all week here at the satellite conference in Washington DC and many people have guessed that the winning bidder would be Amazon. That seemed to be the most likely outcome back in January. However, I think that Jay took Amazon’s offer to SpaceX and they probably decided to beat it, in order to further cement Starlink’s dominance of the satellite industry. Amazon already faces severe competitive pressure from Starlink in the broadband market, and a Starlink purchase of Globalstar would block another opportunity for Amazon to broaden its appeal and match Starlink’s D2D offer.
Buying yet more spectrum might not be seen as the wisest course of action for SpaceX, if some international regulators decide that because Starlink controls Globalstar’s MSS spectrum there is no need to grant Starlink additional rights in the 2GHz MSS spectrum acquired from EchoStar. But Brendan Carr’s threats that he will block European satellite operators from the US market if the EU withdraws Starlink’s spectrum rights should carry the day in the near term.
In particular, a two year extension is likely to be granted for the current EU 2GHz spectrum licenses (which is conveniently beyond the November 2028 presidential election). And 2029 is a long way away, given the number of balls Elon Musk has to juggle in the next few years to get Starship flying, meet NASA’s moon ambitions and sort out the challenges at xAI and Tesla.
What is much less clear, is what will happen to Globalstar’s C-3 constellation and the relationship with Apple after a sale. Would Apple continue to pay Starlink hundreds of millions of dollars per year to support connectivity on existing iPhones? Would the C-3 constellation still be completed, especially if it takes MDA another two years or more, by which time Starlink might have its own next generation Starlink Mobile constellation on orbit? That decision could go either way, depending on how confident SpaceX is that Starship will be ready to launch the next gen constellation on time.
Meanwhile, in other news, it seems that Viasat has concluded that it will have to put some of its own money on the line to get started with the 2800 satellite Equatys constellation, with RocketLab likely to be chosen as the satellite bus contractor. Plausibly, RocketLab’s recent $1B fundraising could be used to provide an equity injection into the Equatys joint venture.
And AST is telling people that it will now rely on New Glenn for 9 of its first 12 launches, implicitly confirming the rumors that the company can’t figure out how to stack satellites within the much smaller Falcon 9 fairing. Of course, there’s no way that New Glenn will provide AST with anything like 9 launches this year, so AST’s deployment plans will be pushed out even further.
The level of skepticism about AST at the conference is quite remarkable, but despite Starlink’s dominance, there’s little reason for mobile operators to withdraw their support in the immediate future. Instead, with Starlink’s next generation Starlink Mobile constellation at least two years away and alternatives including AST, Equatys and Lynk all on a similar timetable, MNOs can wait and see, and perhaps pray, that one or more alternatives to Starlink ultimately emerges, and that, in the meantime, more clarity emerges about whether their customers actually care about D2D at all.
Permalink
03.06.26
Posted in Aeronautical, Operators, SpaceX at 8:29 am by timfarrar
Last Sunday afternoon (4.11pm Pacific time), March 1, Elon Musk posted a curious tweet:

This came in response to another tweet about use of Starlink on US attack drones, but that’s not the important issue (and in fact, as it applies to US-approved uses, the statement is somewhat misleading: Starlink satellites are widely used in Ukraine for military purposes, with funding from the US Department of War, it’s just that SpaceX uses the Starshield brand for these sales, not the “commercial Starlink” service).
Musk’s tweet states that “weapon systems” using Starlink are “shut down when discovered”. So what did Starlink shut down right after this tweet? That became clear on Monday morning, when general aviation users started complaining that their Starlink service had been affected because “effective immediately, the maximum supported in-motion speed for Roam and Priority plans is 100 mph”. Instead Starlink has introduced Aviation 300 and Aviation 450 plans (with much higher pricing) that allow for usage at up to 300mph and 450mph respectively.
But what is even more notable is that the rules for these new plans require you to submit a scan of your passport, as well as details of the aircraft that the Starlink service will be used on. In contrast, all you need to sign up for the Roam plan is a credit card.
So what “weapon system” flies at not much more than 100mph and shouldn’t be provided to certain passport holders? We all know that Russian attack drones have been an issue in Ukraine and Starlink introduced a whitelisting process last month to address this. But it seems no one thought about Iran at that point in time.
And the remaining question is how did Musk “discover” this on Sunday? God forbid that the Iranian drone which killed six US servicemembers earlier in the day in Kuwait (and was described as “flying slow and low to the ground”) was using Starlink…
Permalink
03.02.26
Posted in Aeronautical, D2D, Globalstar, Operators, Regulatory, Services, SpaceX, Spectrum, T-Mobile at 7:36 am by timfarrar
It was fascinating to see today’s announcement at MWC, that Starlink is partnering with Deutsche Telekom to “support over 140M subscribers across 10 European countries“. Most remarkable is that DT is explicitly confirming that “the service will operate only in Starlink’s MSS (Mobile Satellite Service) spectrum”, effectively treating renewal of EchoStar’s existing 2GHz MSS license in Europe as a fait accompli.
That’s perhaps not surprising, because I’m told that an announcement from the EU on the process for reallocating the 2GHz licenses after they expire in spring 2027 remains stalled, and may take several more months to emerge. As a result, the expectation is that the current licenses (held by Viasat and EchoStar) will be extended, probably by two years, to allow time for that process (with appeals and a need for subsequent actions by national regulators) to conclude.
But there is a wider context here to the alignment between Starlink and Deutsche Telekom here, which is seemingly happening with the implicit backing of the German government (and makes me wonder what will happen to Tesla’s factory in Germany this week).
Back in January, news broke that Starlink had struck a fleetwide deal to equip Lufthansa’s aircraft with connectivity. After the prior loss of IAG to Starlink in November 2025, Lufthansa was the last remaining anchor customer for Viasat’s European Aviation Network (EAN).
Lufthansa’s defection fatally undermined the case to retain EAN in its current form and therefore has called into question the need for Viasat to retain 2x15MHz for its 2GHz MSS license. In supporting Viasat’s application for renewal, Lufthansa had even gone as far as to claim that “The EAN is a critical building block in continuing our journey to offer an industry-leading connectivity solution to our passengers.” Of course, it will take some time to replace the EAN terminals on both Lufthansa and IAG, but that just reinforces the rationale for a two-year extension to the current European 2GHz licenses, before any changes take place.
Those changes could potentially reduce both Viasat and EchoStar to paired 10MHz blocks and free up a third license for a European provider (prompting a fight between the AST/Vodafone partnership and the SES/Lynk/Omnispace grouping). But now I wonder if DT might switch its position and suggest cutting Viasat to 2x10MHz, in order to free up 2x5MHz for IoT, while leaving EchoStar/Starlink with the full 2x15MHz. Though whether that would fly with EU regulators is far from clear.
What is interesting is that Lufthansa’s decision to defect to Starlink was apparently very sudden, in fact I’m told that Lufthansa had been negotiating a major deal with another IFC provider for the last couple of years, which was close to being confirmed publicly, and rumors suggest that the German government had a hand in the switch.
Now we have a similar major deal between Deutsche Telekom and Starlink that comes after DT reportedly vetoed T-Mobile US’s plan to buy EchoStar’s spectrum last summer to enhance the partnership between TMUS and Starlink. And last June, DT had been just as unenthusiastic about any changes to the 2GHz band, stating that “Deutsche Telekom AG plans to continue operating the European Aviation Network (EAN) using the MSS 2GHz spectrum beyond 2027…preserving the current spectrum allocation is crucial for the continued operation and economic viability of the EAN.”
So the natural question is “what changed”? I’m told that even after vetoing the TMUS-EchoStar spectrum deal (and then replacing the TMUS CEO while privately characterizing TMUS as “going rogue”), DT continued investigating D2D options and was one of three companies that looked at Globalstar when that asset was put up for sale last fall (the other two being SpaceX and Apple).
But nothing happened there, and now DT has decided instead to strike a major partnership with Starlink, preferring to rely on the 2GHz MSS band over Globalstar’s Big LEO spectrum. And there’s even a DT panelist (Jaroslav Holis) scheduled to speak at the Equatys event on Wednesday which raises the question of what DT might have been exploring there. So I’m left wondering whether there are wider German political factors behind the decisions of both Lufthansa and Deutsche Telekom to reverse themselves in short order.
Permalink
02.08.26
Posted in Broadband, Financials, Operators, Regulatory, SpaceX at 2:29 pm by timfarrar
On Friday, redacted versions of two SpaceX financial forecasts, one from 2021 and the other from 2023, were disclosed in the Delaware litigation between SpaceX shareholders.
While only very limited numbers in the financial projections remain unredacted (beyond the expectation in the 2021 forecast that “government” revenue for Starlink would grow to $5B by 2027), there is enough that can be extracted to determine that Starlink has exceeded the 2021 revenue forecast, but Starship has fallen dramatically behind expectations even in 2023. The 2021 forecast helpfully used redactions matched to the number of characters, showing that Starlink was first expected to exceed $10B in revenues in 2026, while in actual fact Starlink passed $10B in 2025.
The projected valuations on the last page of this document also make it possible to back into the total company revenues forecast in 2021 and 2027: the $102.8B valuation was 25x revenues, implying a revenue forecast of $4113M for 2021. By 2027 this valuation was expected to have increased 4.9x, to around $500B, which was said to be 20x revenues, implying a revenue forecast of ~$25B for 2027. That again is slightly less than SpaceX’s likely total revenues in 2027, even if you remain skeptical about SpaceX’s ability to meet the current published 2026 forecast of $22B-$24B.
However, the 2023 forecast shows how SpaceX was expecting Starship to start launching Starlink satellites to orbit in 2024, with Falcon 9 phased out for Starlink launches in 2026. Now even on Musk’s optimistic timeline from December 2025, Starlink V3 launches on Starship aren’t expected “at scale” until “around Q4″ of this year. So Starship launches of usable payloads have now consistently remained 12 months out for nearly three years.
It’s also fascinating to me how the ongoing debate about orbital data centers tends to ignore launch constraints. SpaceX is just beginning to scale up to develop these “AI satellites”, but until now the emphasis for Starship has been on getting it ready to launch Starlink V3 in volume. That’s meant building extensive launch pad infrastructure in Florida and seeking permission for a high launch tempo there.
Florida is ideal for Starlink launches to 40 and 50 degree inclinations, which will be much more difficult in Boca Chica. However, Florida is a terrible location for sun synchronous launches, which is where these orbital data centers are supposed to go, to utilize maximum sunlight. Back in 2020, SpaceX conducted the first sun synchronous launch from Florida in more than 50 years, and has continued to launch some Transporter rideshare missions to sun synchronous orbits since then, but this requires a very fuel inefficient “dog leg” maneuver and so is only suitable for light payloads, not bulk launches of AI satellites.
Similarly, undertaking sun synchronous launches from Boca Chica would be extremely challenging (and potentially cause an international dispute), as these rockets would need to fly completely across Mexico, not over the open ocean. That’s why Vandenberg is typically used for sun synchronous missions, but SpaceX hasn’t even begun building a Starship pad there, and a high launch tempo is likely to be very politically controversial in California. So how exactly does SpaceX intend to get these AI satellites to the desired orbit?
Permalink
« Previous entries Next Page » Next Page »